FEATURES
All-in-One Retirement Planning—Without the Advisor Fees
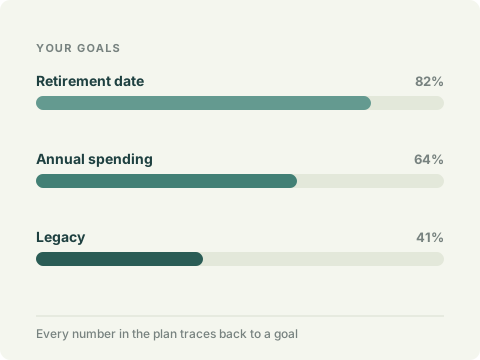
Start with what you actually want. A retirement date, a spending level, something left behind. The plan is built against those goals, so every change shows up as progress or a gap.
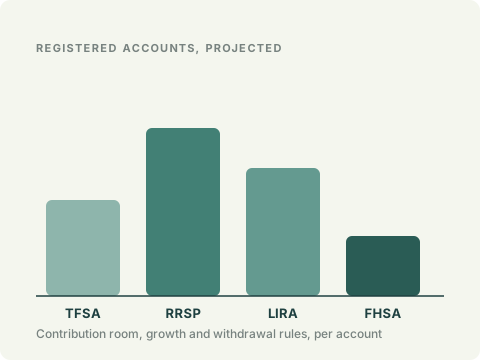
Each account is modelled on its own — contribution room, growth, and the rules that govern withdrawals. LIRA unlocking and RRIF minimums are built in. You see what each account is worth in each year, not one number today.
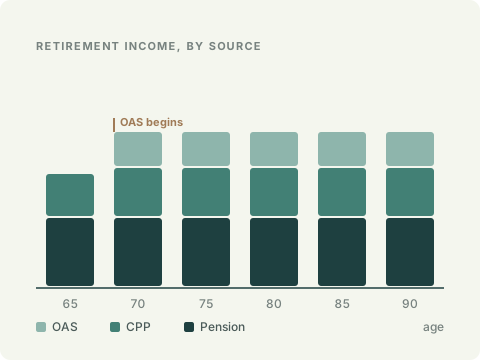
CPP and OAS are decisions. Model taking CPP at 60, 65 or 70 and watch the rest of the plan respond. Defined benefit pensions, bridge benefits and survivor options sit in the same projection.
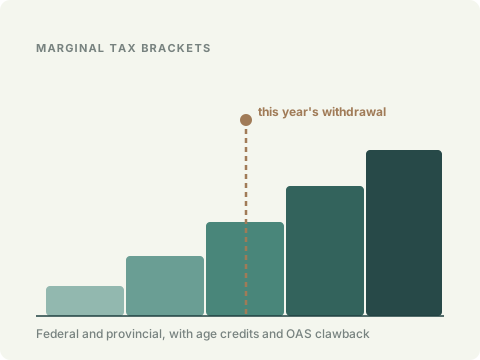
Tax is the largest cost in most retirement plans. Every withdrawal runs through federal and provincial brackets, with age credits, pension splitting and OAS clawback applied. Change a number and the tax moves with it.
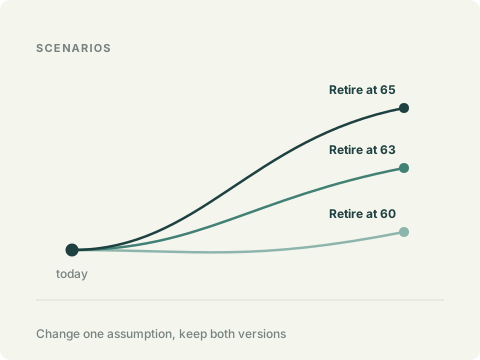
Retire at 60 or 63. Inflation at 2% or 4%. A market that cooperates or one that doesn't. Build the versions side by side and keep the ones worth planning around.
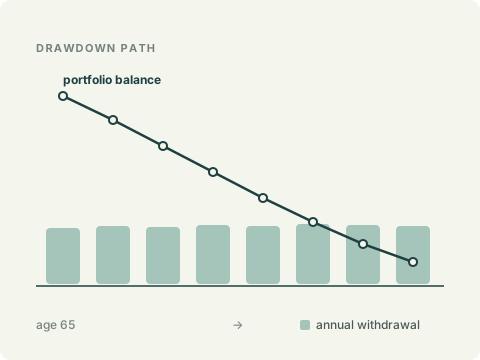
The order you draw from your accounts changes what you keep. See the year-by-year path — which account funds which year, what the balances look like at 85, and where the plan runs thin.
Your data is encrypted and stored on Canadian servers. Nothing is sold, and nobody calls you because you ran a projection. The plan stays yours.
Join a growing number of Canadians who are using data-driven tools to make smarter retirement decisions—with clarity and independence.